
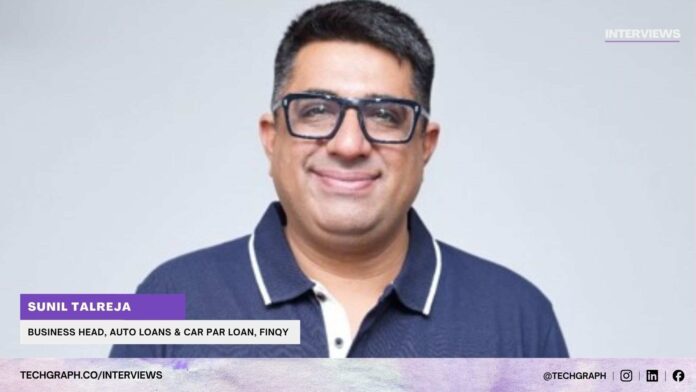

Speaking with TechGraph, Sunil Talreja, Business Head for Auto Loans and Car Par Loan at FINQY, discussed how the rapid growth of India’s used car market has created a large segment of owners who struggle to access formal credit, and how the company is enabling them to unlock liquidity from their vehicles to meet essential financial needs without selling or disrupting daily mobility.
He also spoke about how FINQY’s transparent loan structure gives borrowers the freedom to use funds across personal and business requirements by supporting affordability and financial resilience while maintaining the trust customers expect from regulated and compliant asset-backed lending.
Read the full interview in detail:
TechGraph: For a long time, auto finance in India has been narrowly defined as buying a new car and repaying it in fixed instalments. With Car Par Loan, you are asking people to look at their car in a completely new way. What gap did you see in the market that led you to reimagine this model?
Sunil Talreja: In India, a car is often seen only as a mode of transport or an aspirational purchase. What we noticed is that once a car is bought, it largely becomes a locked asset—even though it has significant value. Traditional lenders never truly tapped into this.
At FINQY, we saw a clear gap: millions of car owners who might have urgent needs for education, healthcare, or business, but were not able to unlock the value of their car without selling it. Car Par Loan reimagines the car not just as a vehicle but as a financial asset that can support a family’s growth and aspirations without disrupting ownership.
TechGraph: One of the most striking features is the option to borrow up to twice the market value of a car, which is far higher than what any traditional loan would allow. What gave you the confidence that Indian customers would be ready to embrace such a shift?
Sunil Talreja: The confidence came from two things: customer behaviour and our credit models. Indian customers are aspirational but also pragmatic—they want liquidity when it’s needed most, but without the burden of losing an asset.
By combining strong risk analytics with transparent structures, we knew we could responsibly offer up to 200% of a car’s value. Early adoption has validated this—customers see it as a smarter alternative to unsecured loans, because it leverages an existing asset without forcing them into high-cost debt.
TechGraph: Financing has usually meant heavy paperwork, long processes, and a lot of waiting. You are instead focusing on instant valuations and a fully digital onboarding experience. Do you think speed is now becoming the most important factor for borrowers, even more than interest rates?
Sunil Talreja: Speed has become critical, especially for today’s digital-first generation. When people face emergencies or opportunities, they don’t want to wait weeks for a decision—they want funds immediately. That said, it’s not about speed versus interest rates; it’s about speed with fairness.
Customers are willing to pay a fair rate if the experience is transparent, quick, and hassle-free. Our digital model—instant valuations, e-KYC, and straight-through processing—ensures we deliver on speed without compromising on trust.
TechGraph: Another big change is that the loan is not tied to car-related expenses. Customers can use the funds for education, healthcare, or even business needs. What are you learning from the way borrowers are actually choosing to use this flexibility?
Sunil Talreja: This flexibility has been one of the most rewarding aspects of Car Par Loan. We’ve seen customers using funds for their children’s education, for urgent medical bills, for expanding small businesses, and even for home improvements.
What this tells us is that liquidity is one of the biggest enablers for the middle-class segment, and giving them freedom of usage makes the product far more valuable. It’s no longer just “a loan against a car”—it’s a financial solution for life’s priorities.
TechGraph: While customers value speed, it also raises concerns about hidden conditions. You have stressed transparency and trusted partners. How are you ensuring that borrowers don’t feel they are stepping into another complicated or unclear loan product?
Sunil Talreja: Trust is central to what we do. At FINQY, we’ve kept the Car Par Loan structure extremely simple: no hidden charges, no fine print surprises. Everything—from valuation to disbursal—is communicated upfront in plain language.
We also work only with trusted financial institutions as partners, ensuring borrowers get a product backed by credible lenders. Our philosophy is that transparency builds long-term relationships; once a customer experiences honesty and simplicity, they’re far more likely to return and refer others.
TechGraph: India’s used car market is now growing faster than the new car market, yet financing in this space has always been difficult. How is Car Par Loan designed to unlock value for used car owners who may have been overlooked by traditional lenders?
Sunil Talreja: The used car market is indeed booming, but traditional lenders have always been cautious because of challenges in valuation, ownership history, and resale. With Car Par Loan, we use tech-driven instant valuations and risk models that consider real-world usage data to make accurate decisions.
This means that even a five- or seven-year-old car can generate significant liquidity for its owner. By doing this, we are turning millions of underutilized vehicles into financial assets—helping owners who were previously excluded from formal credit.
TechGraph: Finally, asset-backed finance is expanding across categories from property to gold and now vehicles. Where do you see car-backed loans fitting into India’s financial landscape over the next few years, and could this change how people view car ownership itself?
Sunil Talreja: Car-backed loans are poised to become a mainstream category in India. Just like gold loans became a household financial tool over the last decade, we believe Car Par Loan can play the same role for vehicle owners.
Over the next few years, as awareness grows, more people will view their car not just as a depreciating asset but as a reliable financial lever. This shift can fundamentally change how families and businesses think about ownership—cars will be seen not only as mobility but also as a source of empowerment in times of need.


