
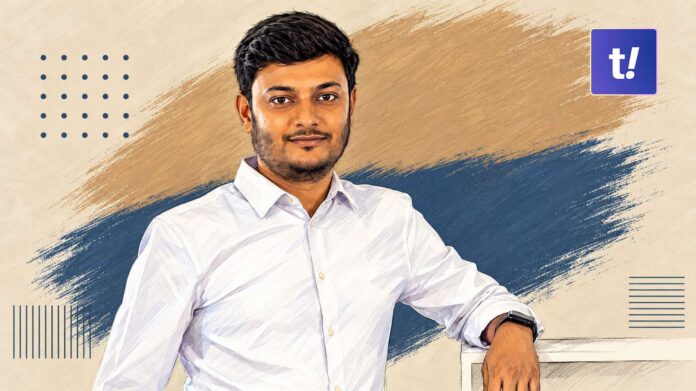

Speaking with TechGraph, Sudharman Ezhil, Director and CEO of NGE Energy, discussed how India’s solar market is entering a phase where the value of a project will increasingly depend on when and how reliably it can deliver electricity rather than how much capacity it adds, and how integrating storage and evacuation as a single system could improve both grid integration and project economics.
He also highlighted the economics of solar projects becoming increasingly sensitive to execution timelines and plant performance, making smooth coordination between development and operations crucial for protecting generation throughout an asset’s lifespan.
Read the interview:
TechGraph: India has added solar capacity at a pace that would have seemed difficult to imagine a decade ago, but the challenges are now shifting from building projects to getting the most out of them. With transmission constraints and curtailment becoming more visible, what do you think needs to change in the way India plans and develops its next wave of solar capacity?
Sudharman Ezhil: For the last decade, India planned solar as a capacity problem — how many megawatts can we add, and how cheaply. That question is largely solved. The binding constraint has moved to evacuation and to when the electricity actually arrives.
Two things need to change. First, land and evacuation should be secured before capacity is bid out, not after. Today, a developer wins a tariff and then discovers that connectivity is eighteen months behind the plant. Second, curtailment risk needs to be priced and allocated explicitly in the PPA rather than sitting silently with the developer, because an unpriced risk simply gets absorbed into a higher cost of capital.
The underlying shift is from selling energy to delivering it at the hour the grid needs it. Once that is the unit of value, storage, transmission and generation stop being three separate planning exercises.
TechGraph: The economics of solar projects are also changing, with developers having to balance competitive tariffs against rising requirements around grid connectivity, equipment sourcing and project execution. From what NGE Energy is seeing across its projects, where are developers facing the greatest pressure on project economics today?
Sudharman Ezhil: The honest answer is that the cushion has gone. For several years, falling module prices absorbed every other cost increase, and tariffs were bid on the assumption that the trend would continue. Module prices have stabilised, domestic content requirements have moved costs the other way, and tariffs have not moved up to meet them.
Where we see the sharpest pressure is on time, not on price. Our own working figure for the cost of delay on a solar project is roughly ₹11,400 per MW per day. On a 50 MW asset, a three-month slip in connectivity — which is entirely outside the developer’s control — is a very large number, and it lands on a project whose revenue was locked at bid stage. Connectivity charges, bank guarantees and GNA obligations compound that, because you are paying to hold a network position you cannot yet use.
TechGraph: The solar supply chain is also going through a major transition as India pushes for greater domestic manufacturing of modules and cells. How is this changing the way you approach procurement and project planning at NGE Energy, particularly when developers have to balance cost, availability and long-term reliability?
Sudharman Ezhil: Procurement used to be a price negotiation. It is now a scheduling and qualification exercise. With ALMM List-II and DCR requirements, the constraint is availability against a specific commissioning window rather than the lowest quotation.
We now book cell and module capacity far earlier in the project cycle, and we fix the bill of materials at bid stage rather than assuming we can buy on the spot market later. If you bid a tariff on generic module assumptions and then discover the compliant product is only available at a premium and on a longer lead time, the project economics have already been decided against you.
Domestic manufacturing is the right direction for the country; the discipline has to be that we industrialise quality at the same pace we industrialise volume.
TechGraph: NGE Energy works across solar EPC, power generation and O&M, giving you exposure to different stages of a project. Where do you see the biggest difference between how a solar project is expected to perform at the planning stage and how it actually performs once it starts generating power?
Sudharman Ezhil: The gap is almost never where the DPR expects it. Module degradation behaves broadly as modelled. What is consistently under-modelled is availability.
A financial model will typically assume the grid is available 99 per cent of the time. In practice, you have backing-down instructions, evacuation constraints, voltage and frequency events, and transmission outages, and those losses are structural rather than occasional. Soiling is the second recurring surprise — dust behaviour in a Tamil Nadu summer or at a coastal site is very different from the generic loss factor applied at design stage, and it interacts with water availability for cleaning.
Third, there is a difference between a plant being commissioned and a plant being stabilised, and that settling period is typically twelve to eighteen months.
Working across EPC, generation and O&M is a real advantage here, and it is deliberate. Because we build plants we then own and operate for 25 years, an optimistic design assumption does not disappear into a handover document. That feedback loop from O&M back into design is, in my view, the most underrated quality mechanism in this industry.
TechGraph: O&M is becoming a much bigger part of the conversation as India builds a larger fleet of operating solar assets. What are you seeing on the ground today in terms of the problems that actually affect generation over time, and how is NGE Energy changing its approach to keep plants performing efficiently?
Sudharman Ezhil: If you rank the causes of lost generation on an operating fleet, catastrophic equipment failure is nowhere near the top. The losses that matter are small, continuous, and invisible without instrumentation.
Grid unavailability and curtailment come first. Then soiling. Then a category I would call silent underperformance — a string or combiner fault, a partially derated inverter, connector degradation, PID on a module bank.
So our approach has moved from scheduled preventive maintenance towards condition-based intervention: string-level monitoring, SCADA analytics that flag deviation against expected rather than against nameplate, drone thermography and IV curve tracing on a rolling basis. We are also moving contractual language away from uptime and towards performance ratio and guaranteed generation, because uptime can be excellent while output is quietly poor.
TechGraph: Storage is becoming increasingly important as India moves from simply adding renewable capacity towards making renewable power more flexible and dependable. How will the growing role of battery storage change the way companies think about generation, evacuation and power delivery as one integrated system?
Sudharman Ezhil: Storage changes what you are actually selling. Today a solar developer sells kilowatt-hours. With storage, we sell shaped, dispatchable power, and that is a fundamentally different product with a different customer conversation.
The most underappreciated effect is on evacuation. A solar plant uses its transmission line intensely for a few hours and leaves it idle the rest of the day. Add storage and the same infrastructure carries far more energy over the year, which improves the economics of a scarce and expensive asset.
That is why generation, storage and evacuation have to be designed as one system rather than sequentially — the right battery size is partly a transmission decision.
TechGraph: Looking ahead, what do you think will become the biggest differentiator in India’s solar industry over the next five years, and how is NGE Energy preparing for that shift?
Sudharman Ezhil: Not price. The differentiator will be the ability to deliver firm, contracted power reliably over decades — which is a test of operating capability and balance sheet, not of construction ability. I would add ownership of grid infrastructure to that. Substation and connectivity assets are becoming genuinely scarce, and control over evacuation will increasingly separate developers who can execute from those who can only bid.
At NGE, we have prepared for this by building the company around ownership rather than handover. We have commissioned over 300 MW, and our model is to develop, build, own, and operate — with long-term O&M agreements that keep us accountable to the asset for its full life. That structure forces long-horizon decisions at every stage, from module selection to tracker design. Combined with the storage and grid work we are doing, it positions us for a market that will reward dependability over the next five years far more than it rewarded speed over the last ten.