
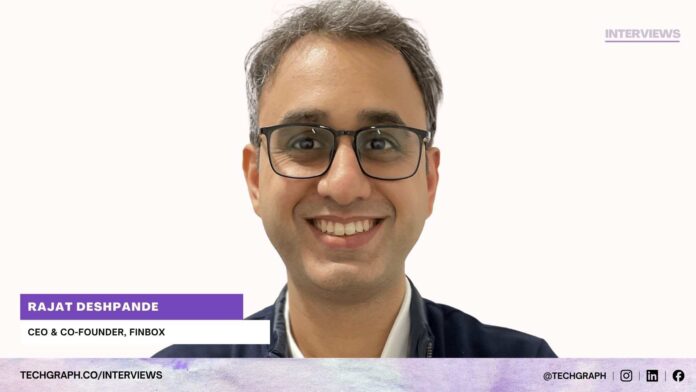

Speaking with TechGraph, Rajat Deshpande, CEO and Co-Founder of FinBox, discussed how embedded finance is moving beyond traditional integrations to become a programmable layer for digital credit, and how the company’s API-first platform addresses these gaps through a unified infrastructure that lets enterprises launch lending products faster while maintaining flexibility.
He also spoke about FinBox’s orchestration stack that helps lenders deliver credit and supports responsible expansion into new customer segments while ensuring consistent governance across partners and channels.
Read the complete interview:
TechGraph: Embedded finance is becoming central to the way businesses engage with their customers. How is FinBox ensuring that its infrastructure enables companies to launch credit products quickly and at scale?
Rajat Deshpande: FinBox enables fast, scalable embedded credit launches with its modular, API-first stack that spans distribution, risk, and data. Our cutting-edge partnership lending stack – FinBox Prism can run multi-partner programs via a single integration with centralized onboarding, offer schemas, as well as routing by lender appetite and eligibility.
This removes the need to integrate multiple vendors, keeps policy and compliance consistent across channels, and pairs underwriting with rich data signals via BankConnect (integrated with AA), DeviceConnect, KYC/enrichment, and FraudScan for responsible scale. This crucial middle layer enables partnerships that deliver capital exactly when and where customers need it, eliminating the technical headaches that cause 60% of lending partnerships to fail.
FinBox currently supports 100+ partners and 2,000+ integrations. We have processed ₹75,000+ crore ($9B+) in applications, and power 50M+ credit decisions/month.
TechGraph: FinBox describes itself as a full-stack credit infrastructure company. How does this translate into a practical advantage for businesses that want to offer credit without building everything from the ground up?
Rajat Deshpande: FinBox’s full-stack model delivers a practical, immediate advantage: a single, modular, API-first platform that spans the entire lending lifecycle—digital onboarding journeys & LOS for origination, Sentinel AI for real-time, no-code policy design and decisioning, Prism for multi-partner orchestration, and integrated data rails (BankConnect AA, DeviceConnect, KYC/enrichment, FraudScan).
Rather than depending on multiple vendors, businesses plug into one stack, launch contextual credit in weeks, and maintain uniform policy and compliance across channels through policy-as-code, consent management, encryption, audit logs, and controls aligned to RBI Digital Lending, DPDP, and AA on a SOC2 Type II/ISO27001 foundation.
The result is faster time-to-market, lower integration and operating costs, and enterprise-grade governance at scale.
TechGraph: Many businesses that access credit through your platform may not have traditional credit histories. How does FinBox design its systems so that partners can extend credit with confidence to such customers?
Rajat Deshpande: We are solving the thin-file/new to credit (NTC) challenge with FinBox DeviceConnect—a consent-led, device data–based credit worthiness evaluation platform that assesses borrowers in real-time. By using privacy-safe device signals to capture everyday repayment intent and ability beyond bureau history, lenders get a sharper risk view and can approve with confidence.
It’s live at scale, assessing 5M+ borrowers each month, and has helped our partners achieve 35%+ higher approval rates and lower credit costs by over 20%, enabling responsible expansion into underserved segments without building bespoke data pipelines.
TechGraph: Risk intelligence often determines the success or failure of digital lending. What approaches has FinBox developed to assess borrowers more accurately in India’s diverse and fragmented market?
Rajat Deshpande: FinBox tackles India’s fragmented credit landscape with a risk-intelligence layer that fuses richer data with policy agility. Our risk intelligence combines BankConnect, DeviceConnect, Account Aggregator (AA) rails, and FraudScan to score borrowers accurately across India’s diverse segments.
BankConnect uses bank statements or consented AA data to fetch transactions to power cash-flow-based underwriting and spot risky borrowers, lifting approvals while controlling risk (partners report ~+35% approvals and ~-54% fraud on these flows). DeviceConnect brings privacy-safe mobile device-based signals to evaluate thin-file/new-to-credit users in real time, helping lenders expand access with control (35%+ higher approvals and 20%+ lower credit costs observed). AA ensures standardized, consented access to financial data across institutions, improving coverage beyond bureau history.
Finally, FraudScan layers impersonation, synthetic, and mule-pattern checks into the journey, so only genuine users are approved. Together, these components deliver contextual, data-rich decisions at scale, suited to different products, geographies, and partner channels.
TechGraph: Regulations around digital lending in India have become more stringent in recent years. How is FinBox adapting its model to help partners remain compliant while still keeping credit products flexible and fast to launch?
Rajat Deshpande: FinBox adapts to stricter digital-lending rules by operationalizing compliance in the product itself while keeping launches fast. It encodes RBI Digital Lending, DPDP, and Account Aggregator requirements as policy-as-code with consent management, encryption, access controls, and audit-ready logs—so policies, notices/consents, and data flows are enforced uniformly across channels.
Additionally, its no-code policy engine let risk teams design, simulate, and promote credit policies quickly, and its orchestration layer standardizes partner integrations,maintaining governance without dependency on more than one vendor.
FinBox also works with lenders and industry bodies to interpret new circulars and update workflows rapidly, giving partners a compliant foundation that still supports flexible products and faster time-to-market.
TechGraph: The lending market is increasingly competitive, with banks and fintech startups both pushing new offerings. What gives FinBox’s infrastructure an advantage that others will find difficult to replicate?
Rajat Deshpande: FinBox is the only plug-and-play, end-to-end digital lending stack that spans both distribution and risk. Its platform products – LOS, Partnership lending stack (Prism) and BRE Sentinel AI digitise the customer journey across channels. Its other API business covers bank-statement analysis, enriched alternate-data underwriting, a KYC suite, and a highly flexible BRE to help lenders keep the risk in control.
In practice, when lenders partner with FinBox, they avoid stitching 3–4 vendors, keep policy and compliance consistent across channels, and unlock material efficiency across the credit value chain.
TechGraph: Lastly, as digital credit infrastructure matures in India, what long-term role do you see FinBox playing in reshaping how businesses and consumers experience credit, and how do you expect that vision to evolve over the next five years?
Rajat Deshpande: FinBox’s long-term role is to be the operating layer for digital credit—the backbone that lets businesses ship contextual credit in weeks while keeping risk and governance consistent across every channel.
For consumers and MSMEs, that translates into fair, transparent, in-context credit that arrives when needed, based on real signals (transactions, platform flows, device intelligence) rather than just legacy bureau history.
Success is measured not only by disbursements, but by how many underserved borrowers are reached and how many businesses are enabled.
Over the next five years, FinBox wants to channelise its focus on:
- GenAI-assisted policy design, agentic back-office co-pilots, and stronger fraud/collections to reduce time-to-launch and operating drag
- New modules like invoice discounting, micro-insurance bundles, and medium-term, embedded savings/wealth, plus a data marketplace.
- Expanding to more high-potential emerging markets (e.g., Southeast Asia, Africa) by 2027 while compounding multi-partner distribution at home.
The goal for 2030 remains clear: fair, transparent credit for 100 million MSMEs and consumers, delivered through infrastructure that makes lending programmable, compliant, and profitable at scale.


